

Since 2017, gaming funds have announced 100 fundraisings and raised $11.2B between them, counting disclosed sizes (some are targets) by vintage year. This report tracks who raised it, who manages it, and what has changed in how mobile studios get funded. Data cut 13 October 2026; the UA provider ranking covers the twelve months to 23 October 2026.
Three things stand out. The market has moved through three distinct cycles, and 2026 is already ahead of 2025 on capital. A small group of managers holds most of the money. And for mobile studios, UA financing has gone mainstream next to early-stage funding: in the first three quarters of 2026 it accounted for 61.0% of the capital across early-stage investment and UA financing combined, or 39.5% without 11 PvX facilities that name no studio.
Three cycles, and a 2026 rebound
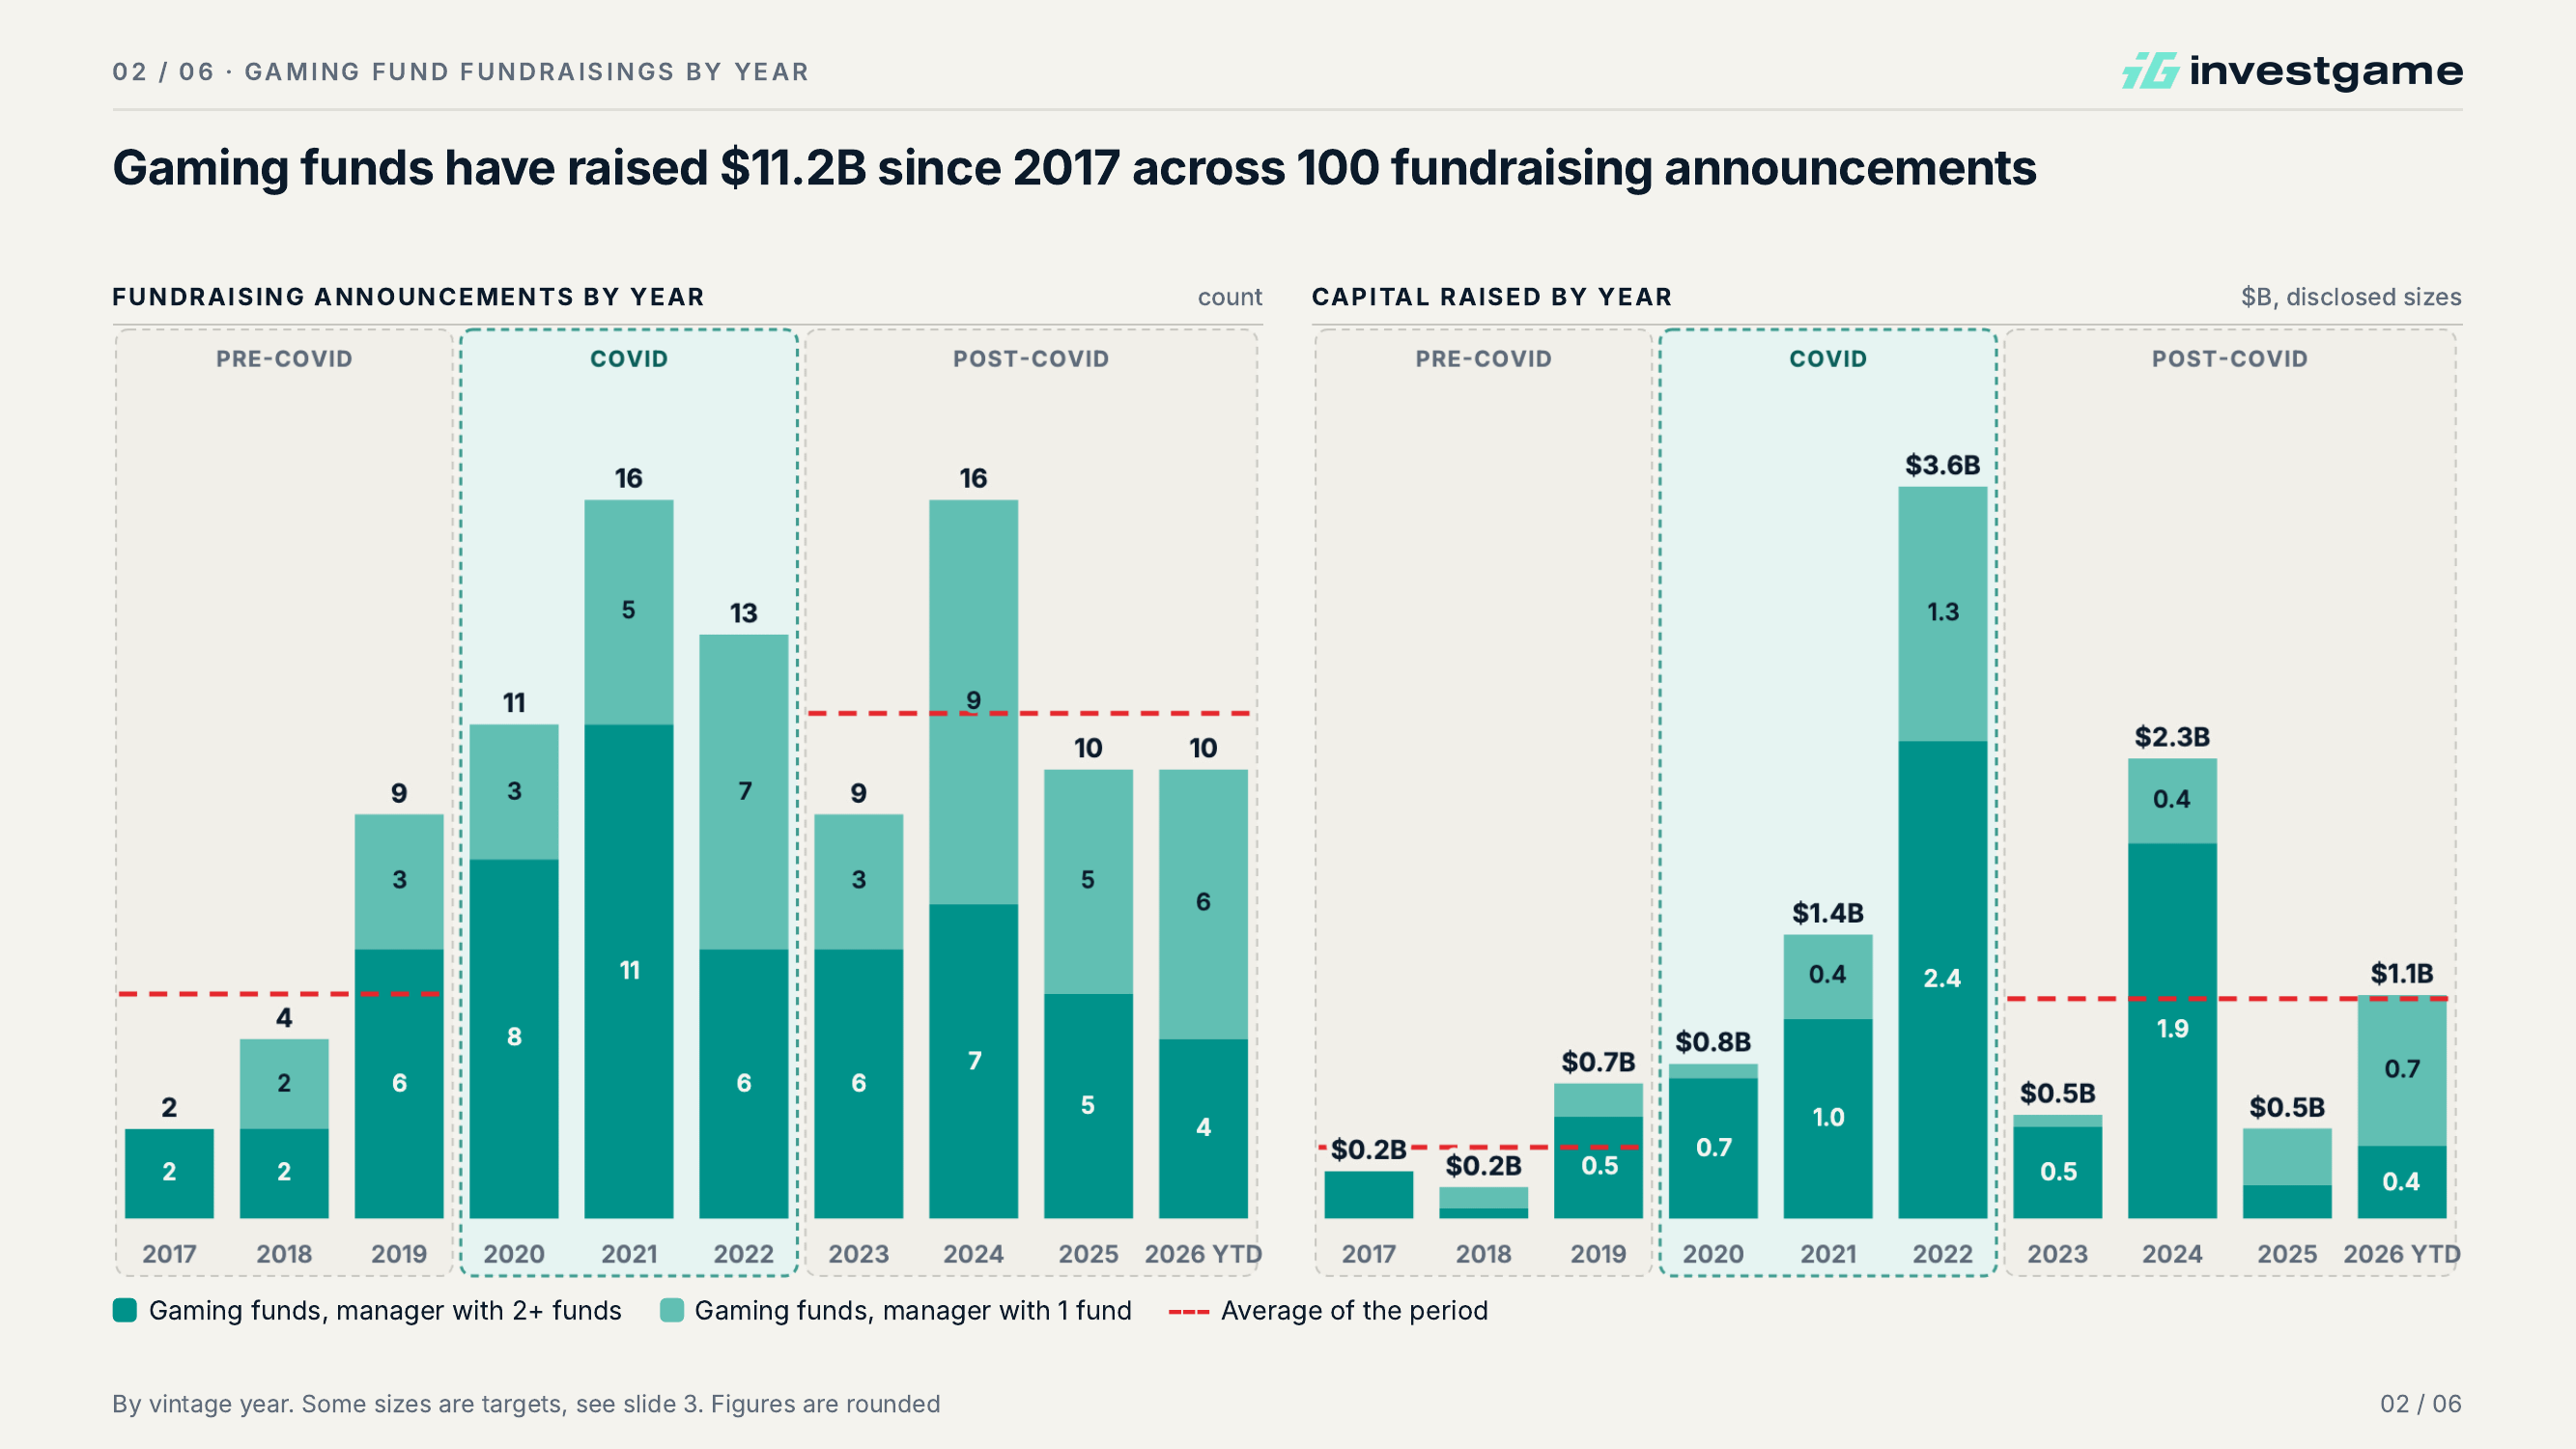
Announcements and capital raised by vintage year, split by managers with 2+ funds and managers with 1 fund. Disclosed sizes; some are targets. Figures are rounded. Source: InvestGame Gaming Funds: Fundraising Overview, October 2026.
Pre-COVID, 2017 to 2019: the market was small. 2 announcements and $0.2B in 2017, 4 and $0.2B in 2018, then 9 and $0.7B in 2019.
COVID, 2020 to 2022: the capital peak. Announcements rose to 11 in 2020, 16 in 2021 (a count only 2024 has matched) and 13 in 2022, while capital went from $0.8B to $1.4B and then to $3.6B in 2022, the largest year in the series. Managers with 2+ funds made 8 of the 11 announcements in 2020 and 11 of 16 in 2021, and raised $2.4B of the $3.6B in 2022, a year in which managers with 1 fund made 7 of the 13 announcements.
Post-COVID, 2023 onwards: a reset, then a swing. 9 announcements and $0.5B in 2023, 16 announcements and $2.3B in 2024 ($1.9B of it from managers with 2+ funds), 10 and $0.5B in 2025. 2026 YTD already has 10 announcements and $1.1B, ahead of all of 2025 on capital. This year, managers with 1 fund account for 6 of the 10 announcements and $0.7B of the $1.1B.
Most of the money sits with ten managers
The top 10 VC managers by cumulative announced fund size hold $7.2B, or 64% of the $11.3B announced by gaming funds since 2011, UA financing excluded. Four of them have crossed the billion-dollar mark on announced sizes: Griffin Gaming Partners at $1.6B, Makers Fund and Andreessen Horowitz at $1.2B each, and BITKRAFT Ventures at $1.1B, where several fund sizes are targets, maximums or announced sizes rather than amounts raised.
Most managers raise only once. Of 65 distinct managers of gaming funds since 2011, 46 raised a single fund, 7 raised two, and only 12 raised three or more. The top ten are where the capital concentrates; their gaming funds, with year and size where disclosed, are in the paid section below.
UA financing goes mainstream for mobile studios
The most notable shift in the report is not in who manages the money but in how mobile studios raise it. UA financing went from a single deal in Q2 2025 to 10 deals in Q3 2025, dipped to 4 in Q4 2025 and climbed back to 10 in Q3 2026. UA amounts are committed amounts, and the 61.0% share for 2026 comes with the 39.5% caveat for facilities with no named studio.
Below: who provides it and how much they have committed, which VC and PE funds provide UA financing, and what the large generalist funds are doing in games.
Keep reading
Paid subscribers get the rest of this post and the full 6-slide PDF. Here is what’s inside:
The top 10 VC managers, fund by fund. Griffin, Makers, a16z, BITKRAFT, Hiro, Play Ventures, vgames, Galaxy, Courtside and Konvoy: every gaming fund in the table, with year, name and size where disclosed, plus the 2026 vehicles.
UA financing against early-stage investment, quarter by quarter. Nine quarters of early-stage and UA capital in $M, Q3 2024 to Q3 2026, and the top 3 UA providers by deals led over the last twelve months, with deal counts and disclosed value.
The UA financing map. Ten more specialized UA providers, and five VC and PE funds providing UA financing.
Generalist funds in games. Four large generalist funds, their latest fundraise since 2024 and all their gaming deals to date: Bessemer, Balderton, Shamrock and e2vc, with selected gaming investments.
The full PDF. All 6 slides, with the footnotes on fund sizes, targets and first closes.